Financial transparency is not a matter of publishing every number an organization holds. It is the disciplined practice of making relevant financial information accurate, understandable and available to the people who need it, while protecting confidential or competitively sensitive details.
That distinction matters. An organization can issue a lengthy report and still leave readers unable to understand its cash position, commitments or progress against plans. Transparency is most useful when it helps people make informed decisions, not when it simply increases the volume of information.
Table of Contents
- What financial transparency means
- Why it matters across an organization
- Match the information to the audience
- Build a workable transparency practice
- Transparency needs boundaries
- How to tell whether it is working
What financial transparency means
Financial transparency combines reliable records, clear explanations and consistent access. It applies to external communications, such as statements for investors or funders, and to internal information that helps teams understand budgets, spending authority and financial results.
The OECD’s 2023 Principles of Corporate Governance describe timely, accurate disclosure of material matters as a core part of corporate governance. They also recognize that disclosure should focus on material information and need not expose details that could harm competitive position when that detail is not needed to inform investors.
In practice, the aim is a dependable picture rather than maximal disclosure. Useful financial communication helps readers understand what happened, why it matters, and what assumptions or uncertainties affect the figures.
Why it matters across an organization
It improves the quality of decisions
Managers make choices about hiring, purchasing, investment and timing with incomplete information. Timely budget-to-actual updates can reveal whether a plan is still feasible or whether assumptions need to be revisited. Cash-flow information also answers a different question from profit: a profitable organization may still need to manage the timing of receipts and payments carefully.
When teams can see the relevant constraints and understand how results are measured, planning conversations can focus on trade-offs rather than on reconciling conflicting versions of the numbers.
It clarifies accountability
Clear financial records make it easier to connect resources with approved plans and responsibilities. That does not mean every staff member needs access to every account or transaction. It means people should know which decisions they own, what financial information informs those decisions, and where approval or review is required.
The U.S. Government Accountability Office’s Green Book frames internal control as a way to support effective operations, reliable reporting and compliance. It is a required standard for federal executive agencies, while the GAO notes that other organizations may also use it as a framework. Its practical lesson is broadly useful: dependable reporting rests on processes and responsibilities, not on a spreadsheet alone.
It supports informed stakeholder relationships
Investors, lenders, employees, members, grant makers and suppliers may each need a different view of an organization’s finances. Consistent explanations can help those audiences assess performance and understand the organization’s capacity, commitments and priorities. Transparency supports informed discussion; it does not guarantee agreement or remove financial uncertainty.
Match the information to the audience
The same underlying records may need to be presented differently for a board, department lead, employee or external stakeholder. The table below is a practical planning guide, not a reporting rule: the right format and level of detail depend on the organization, audience and applicable requirements.
Build a workable transparency practice
Start with a consistent reporting rhythm
Set a practical schedule for budgets, management accounts, forecasts and external reporting. A regular cadence helps people compare periods and notice changes early. The appropriate frequency depends on the organization’s size, operations, governance and reporting obligations.
Standardize definitions as well as dates. If different teams use “revenue,” “committed spend” or “available budget” differently, a report can look precise while encouraging inconsistent interpretation.
Explain variances, not just totals
A number becomes more useful when it is paired with context. A short explanation of a material variance can distinguish a timing difference from a change in demand, cost or underlying assumptions. Where forecasts are used, make clear which figures are actuals, which are estimates and what conditions could change the outlook.
A practical reporting pack often includes:
- Actual results compared with the approved budget and, where relevant, the prior period.
- A cash-flow view that shows expected receipts, payments and timing considerations.
- Notes on material variances, assumptions and emerging risks.
- A clear owner and next review date for decisions or follow-up actions.
Connect reporting to controls
Controls make the numbers more dependable. Depending on the organization, they may include documented approval limits, separation of key duties, reconciliations, restricted system access and review of unusual entries. The design should fit the scale and complexity of the work; procedures that are too cumbersome can be difficult to maintain consistently.
For organizations seeking a structured starting point, the GAO Green Book organizes internal control around components including risk assessment, control activities, information and communication, and monitoring. The framework emphasizes that documentation and ongoing review should reflect an organization’s objectives and circumstances.
Transparency needs boundaries
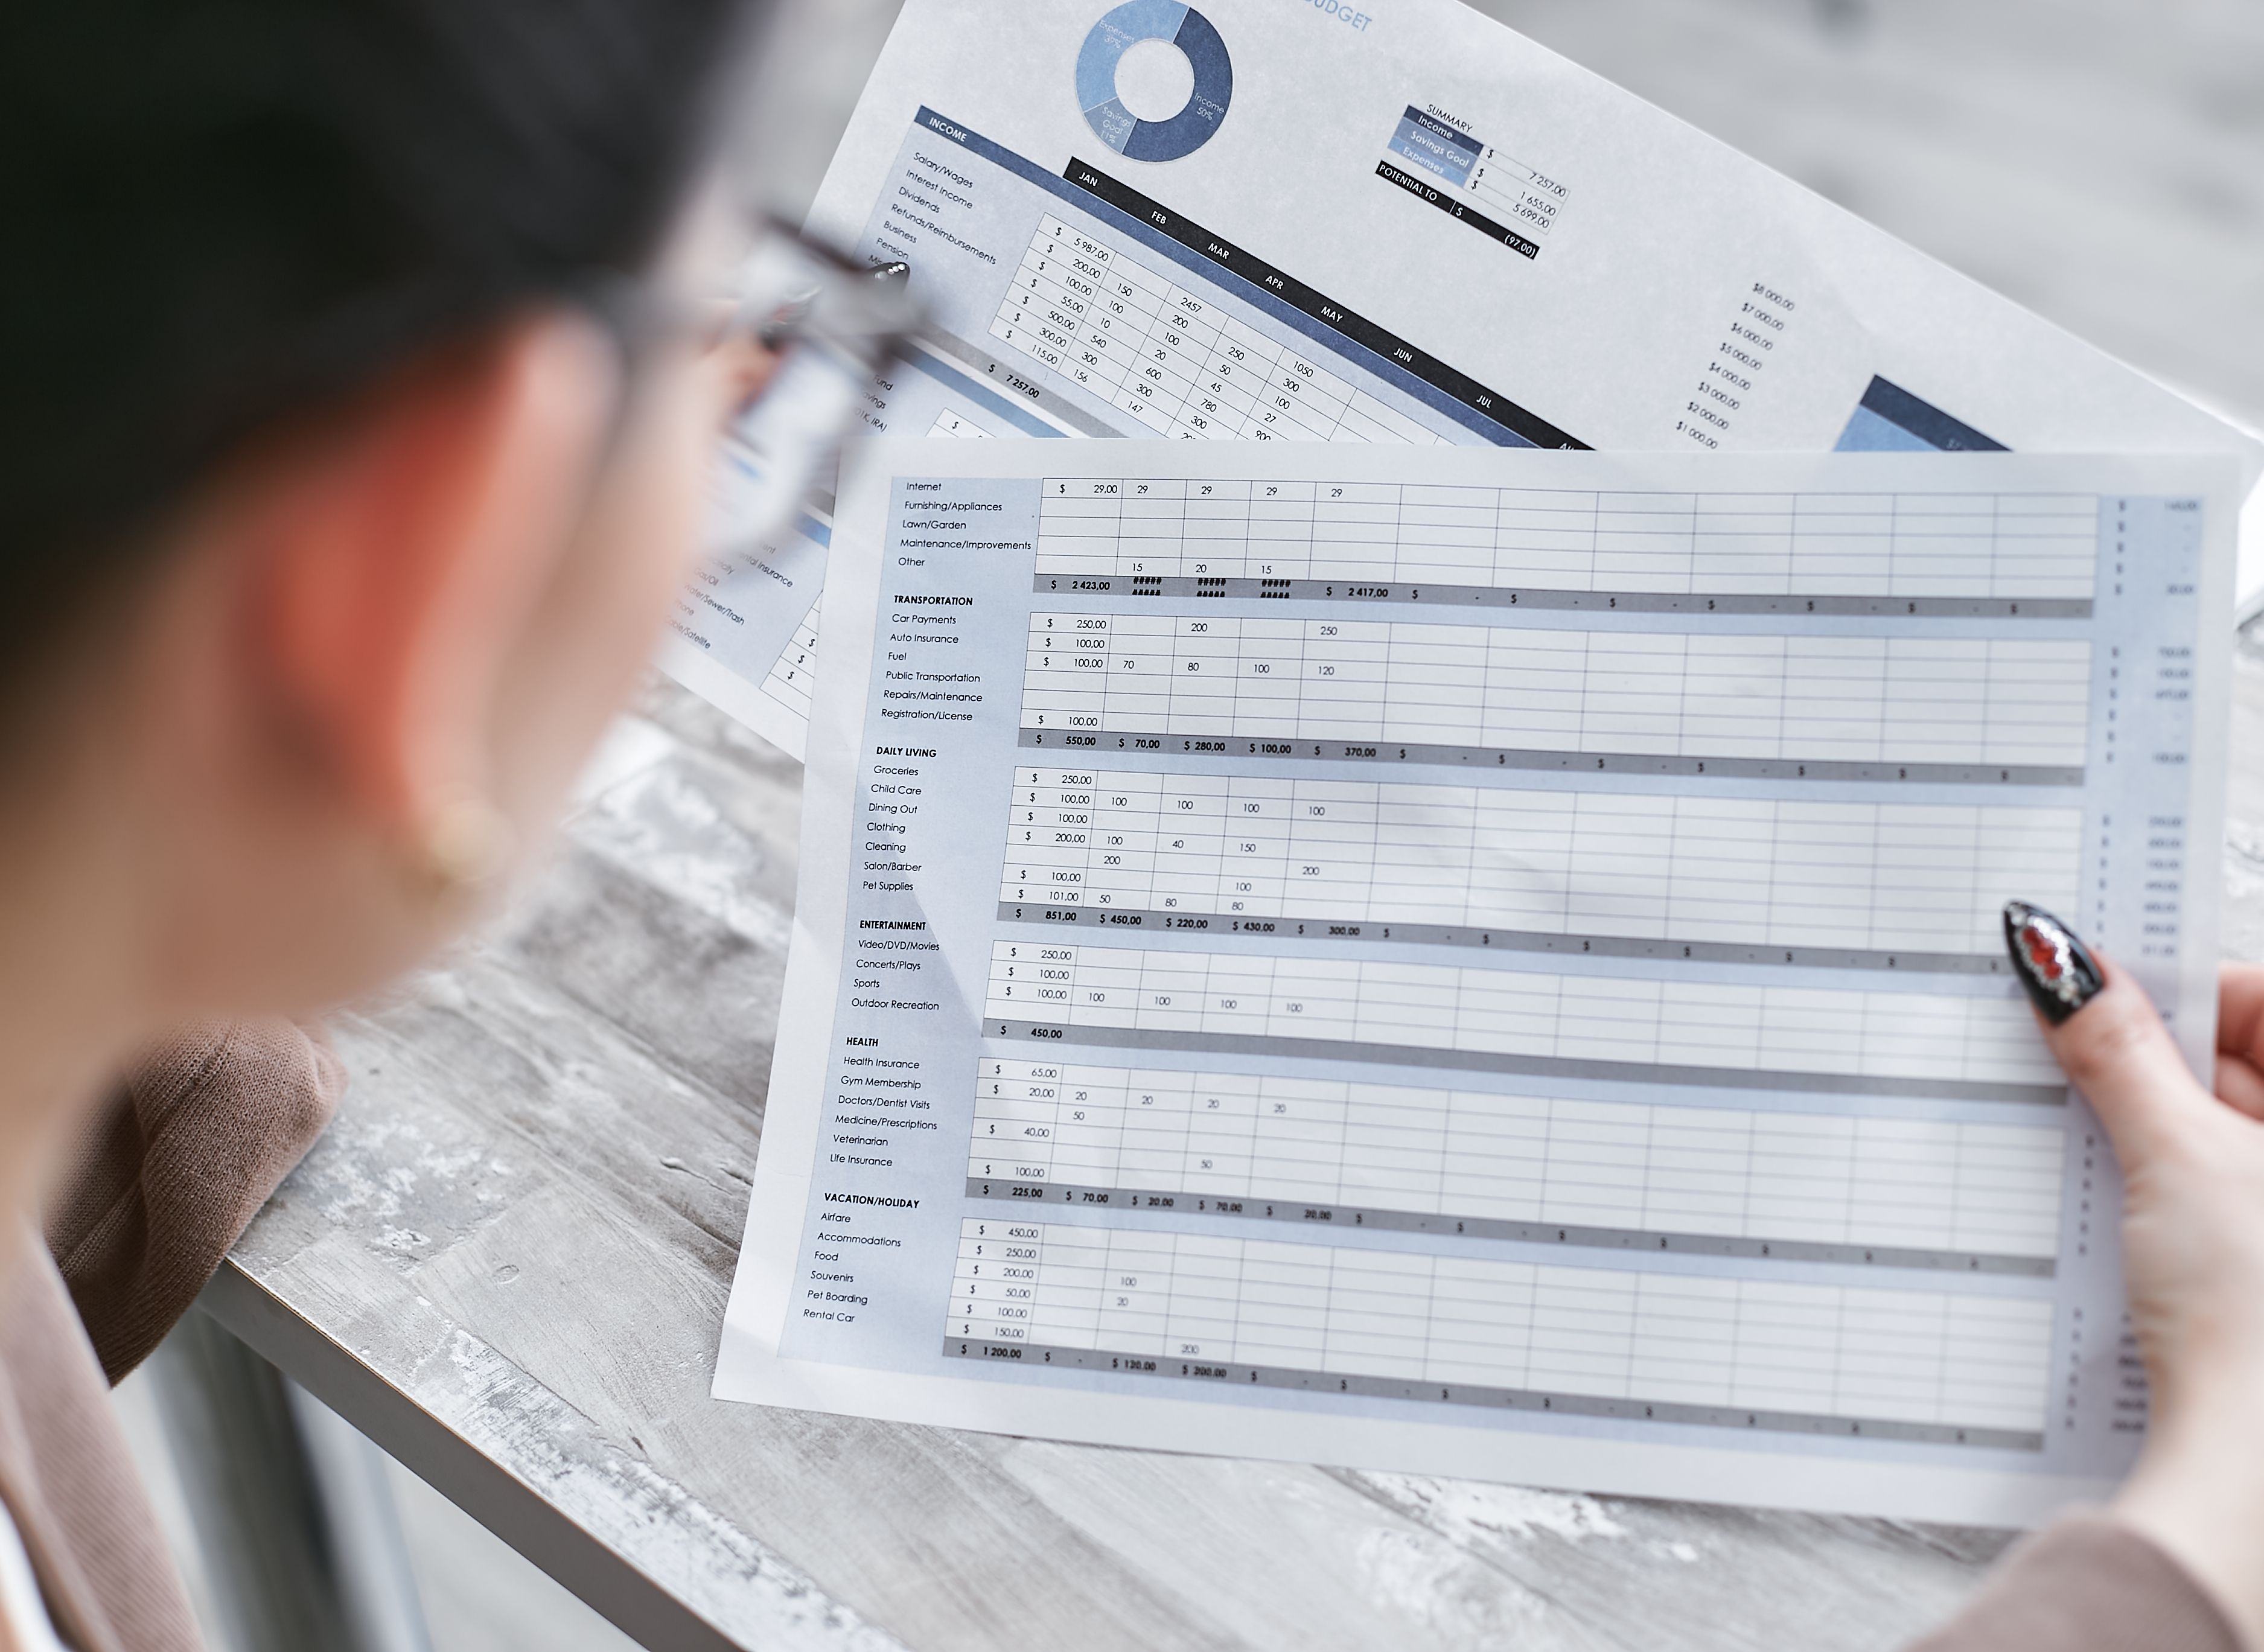
Transparency is not the same as open access to every record. Payroll details, personal data, security-sensitive information, contract terms and commercially sensitive plans may need restricted handling. Legal obligations and reporting expectations also vary by jurisdiction and organizational structure.
The useful question is not “Can this information be published?” in isolation. Ask who needs it, for what decision, at what level of detail, and through which appropriate channel. A summary may give stakeholders the context they need while protecting private or sensitive underlying records.
For an external reader, a brief explanation of reporting scope can prevent overinterpretation. State the period covered, whether figures are audited or unaudited where relevant, the basis used to prepare them, and any important limitations or estimates.
How to tell whether it is working
Financial transparency is working when people can use the information appropriately, not simply when more documents are produced. Organizations can review the process by asking:
- Do intended readers receive reports in time to inform the decisions they make?
- Can budget owners explain significant variances using consistent definitions?
- Are important assumptions, commitments and uncertainties visible to the right decision-makers?
- Can the organization trace key figures to supporting records and assigned review responsibilities?
- Do stakeholders know where to find the relevant information and whom to ask about it?
A useful starting point is to treat financial reporting as a decision-support process: statements and explanatory notes should help readers understand resources, obligations and results over a defined period. The specific reports an organization needs will depend on its purpose and applicable requirements.
A clearer financial picture is a management tool
Modern organizations operate with changing costs, plans and stakeholder expectations. Reliable financial transparency gives decision-makers a common reference point: what the organization has achieved, what resources are committed, and where assumptions may need attention.
The strongest approach is neither maximum disclosure nor a report for its own sake. It is relevant information, explained plainly, supported by sound processes and shared with the right people at the right time. When those elements work together, financial transparency becomes part of how an organization plans and learns, not just how it reports.